Posted Tuesday 3rd November 2026
Overview
Despite lots of rumours and pre-budget scaremongering about equalisation of Capital Gains Tax (CGT), Wealth Taxes, Exit Taxes etc. the first budget from new Chancellor John Healey delivered nothing too dramatic for business or investment in the UK and there were certain headline grabbing changes which seemed to be very supportive of founders and entrepreneurs.
There were no changes to the headline CGT rates which remain unchanged at 18% (basic) and 24% (higher rate). This still feels competitive compared to the average rate across G7 countries of 27.3%.
Key Changes of note:
Founders’ Relief
A new CGT relief giving a 10% rate on up to £10m of lifetime gains, against a top CGT rate of 24%. It applies to qualifying share disposals on or after 6 April 2027 and is aimed at founders and significant early investors in high-growth, innovative UK companies. The maximum saving is £1.4m per individual.
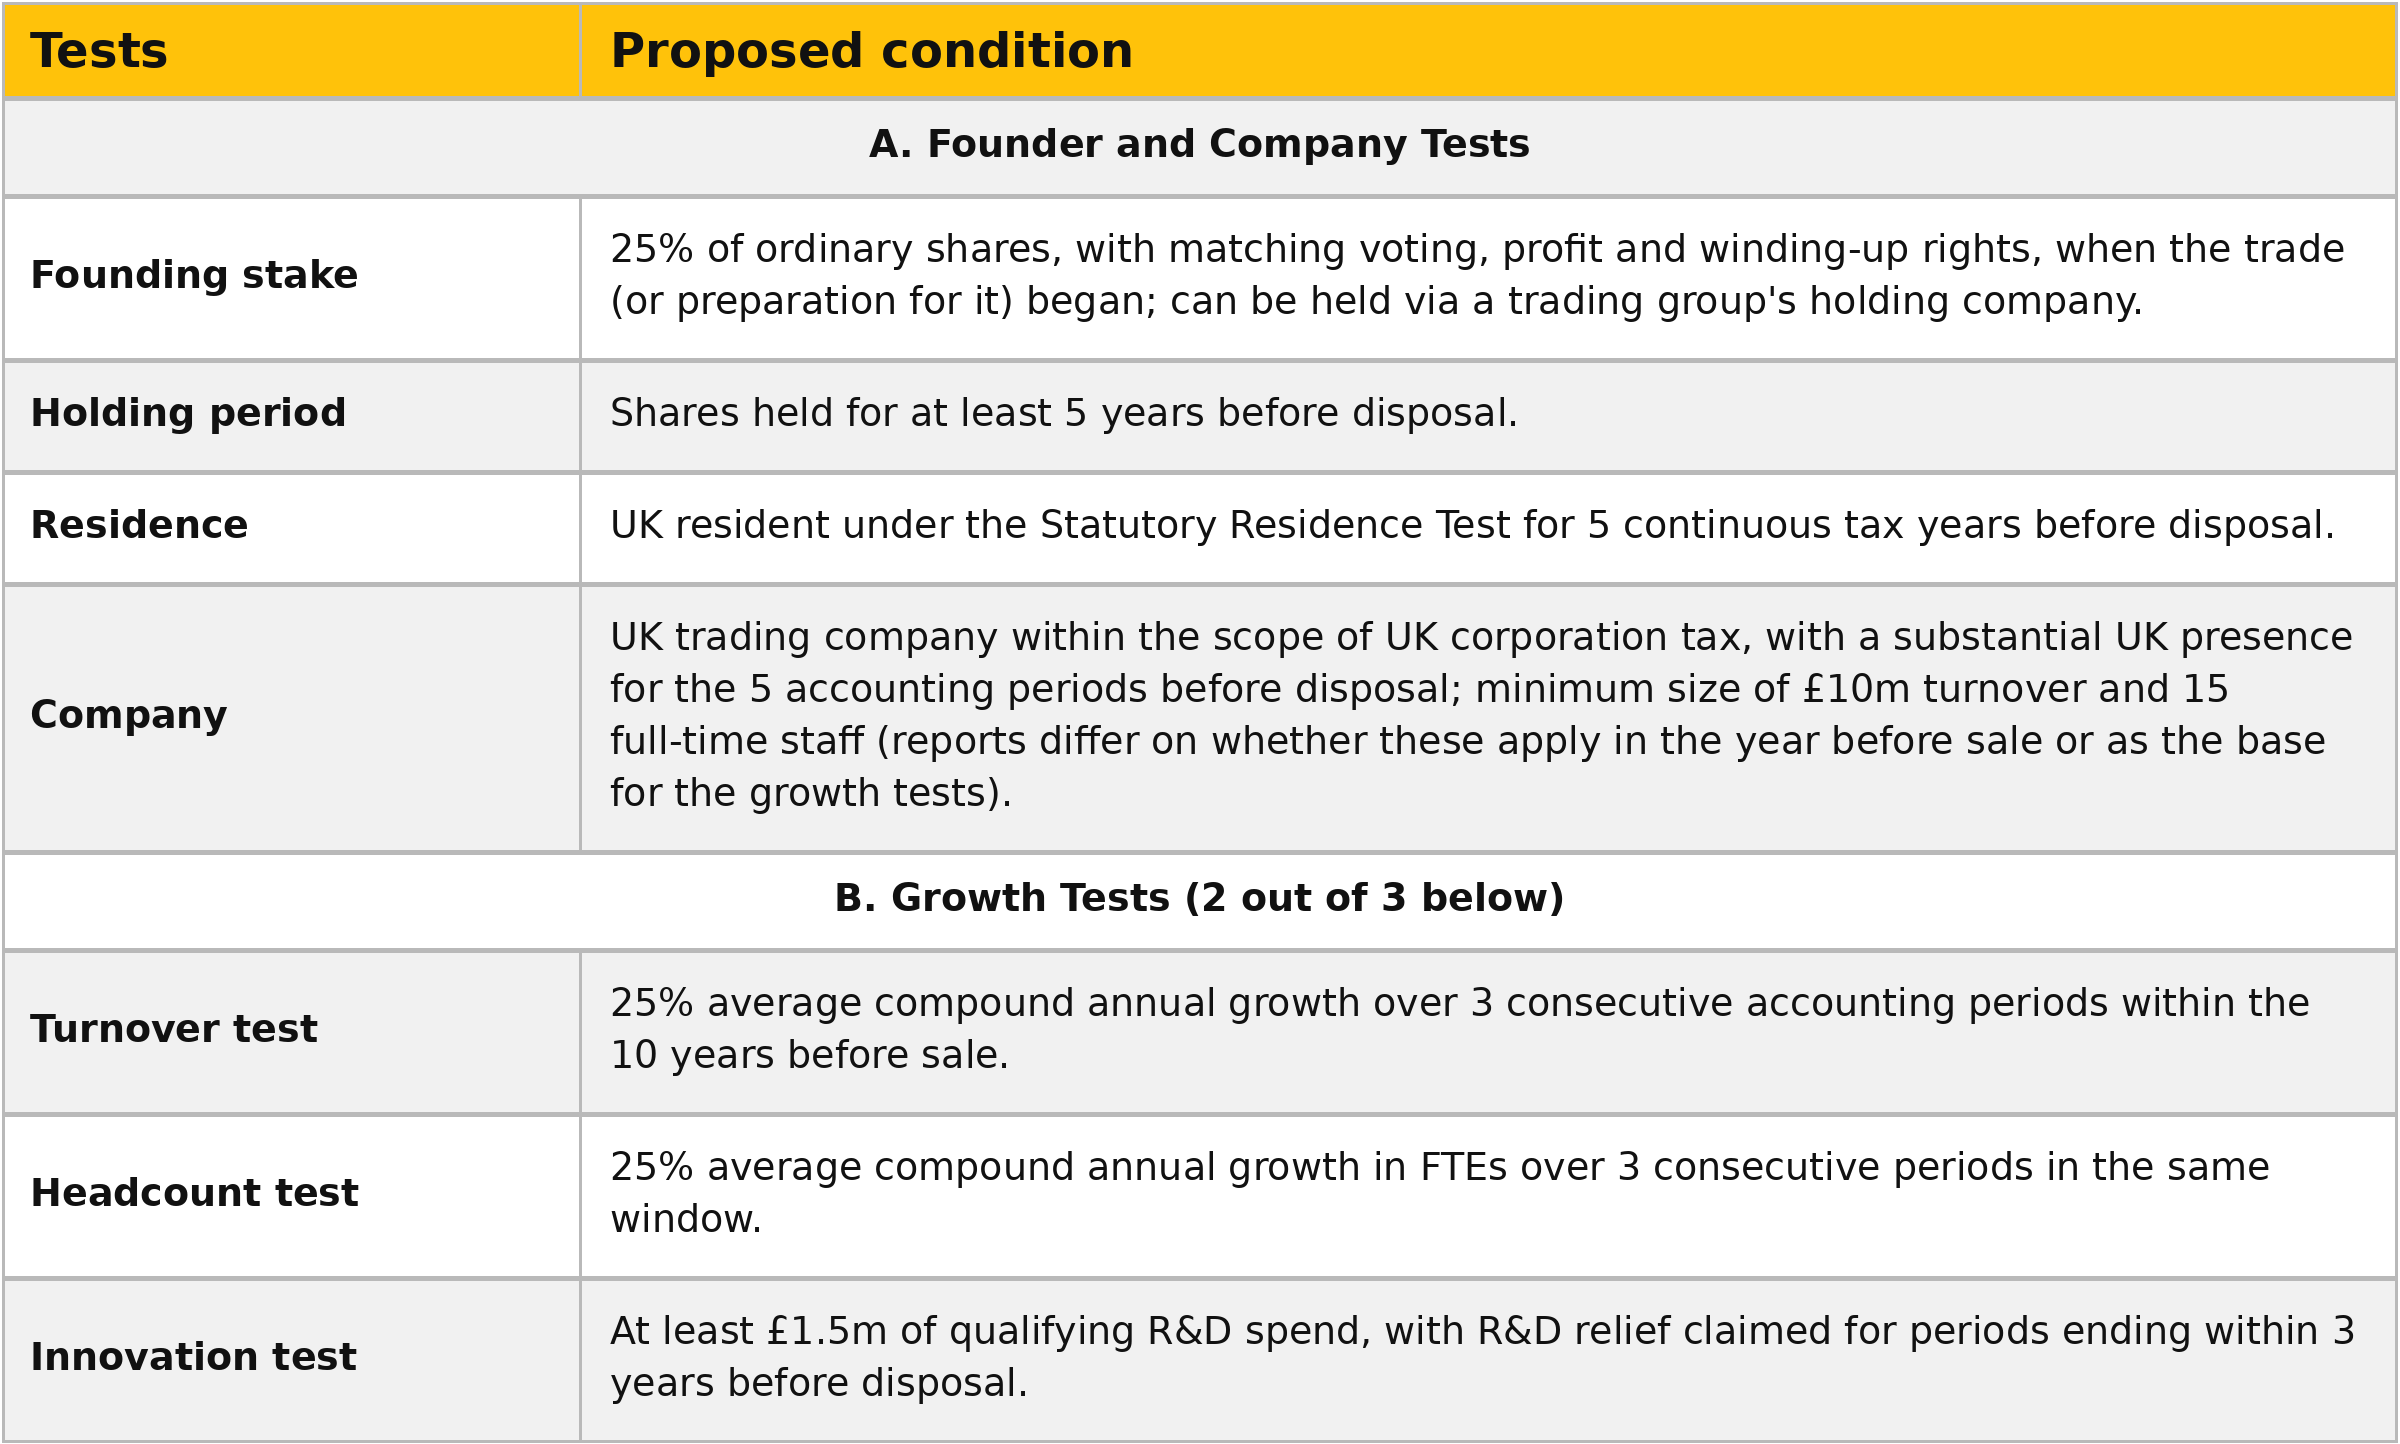
Proposed conditions (HM Treasury technical consultation)
All individual and company conditions must be met, plus at least two of the three growth and innovation tests
Key Points to note
The technical consultation with HMRC closes at 11:59pm on 30 November 2026.
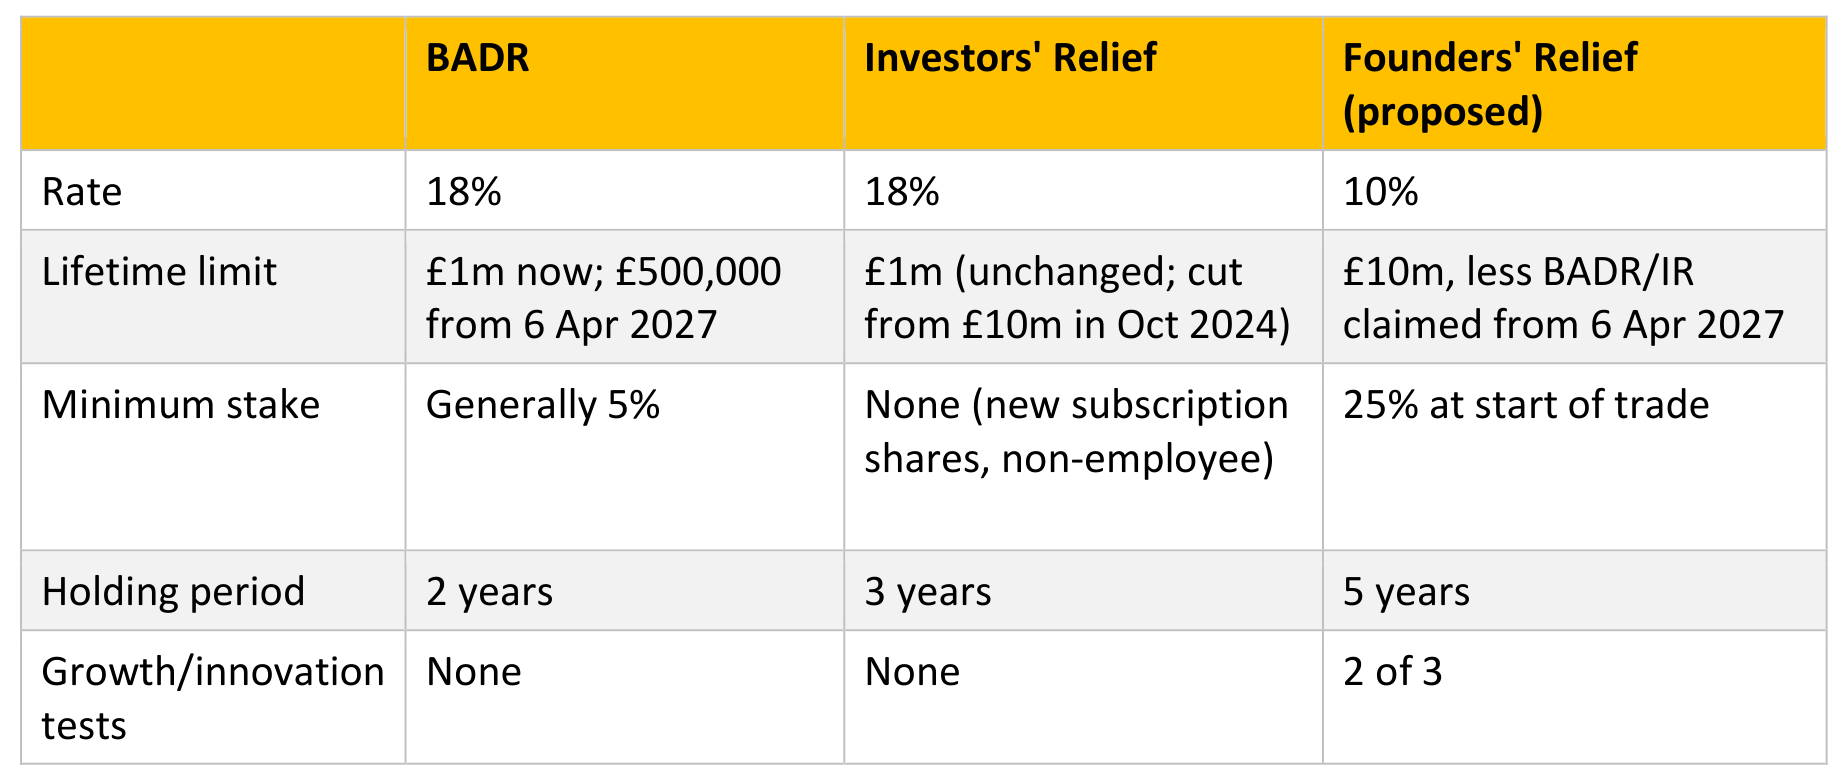
BADR and Investors’ Relief
BADR is halved from 6 April 2027; Investors’ Relief is not changed directly, but both now interact with Founders’ Relief.
EMI2 and EMI changes
From 6 April 2027 CSOP becomes EMI2, with double the individual limit and no overlap with EMI, giving scale-ups that outgrow EMI a stronger fallback.
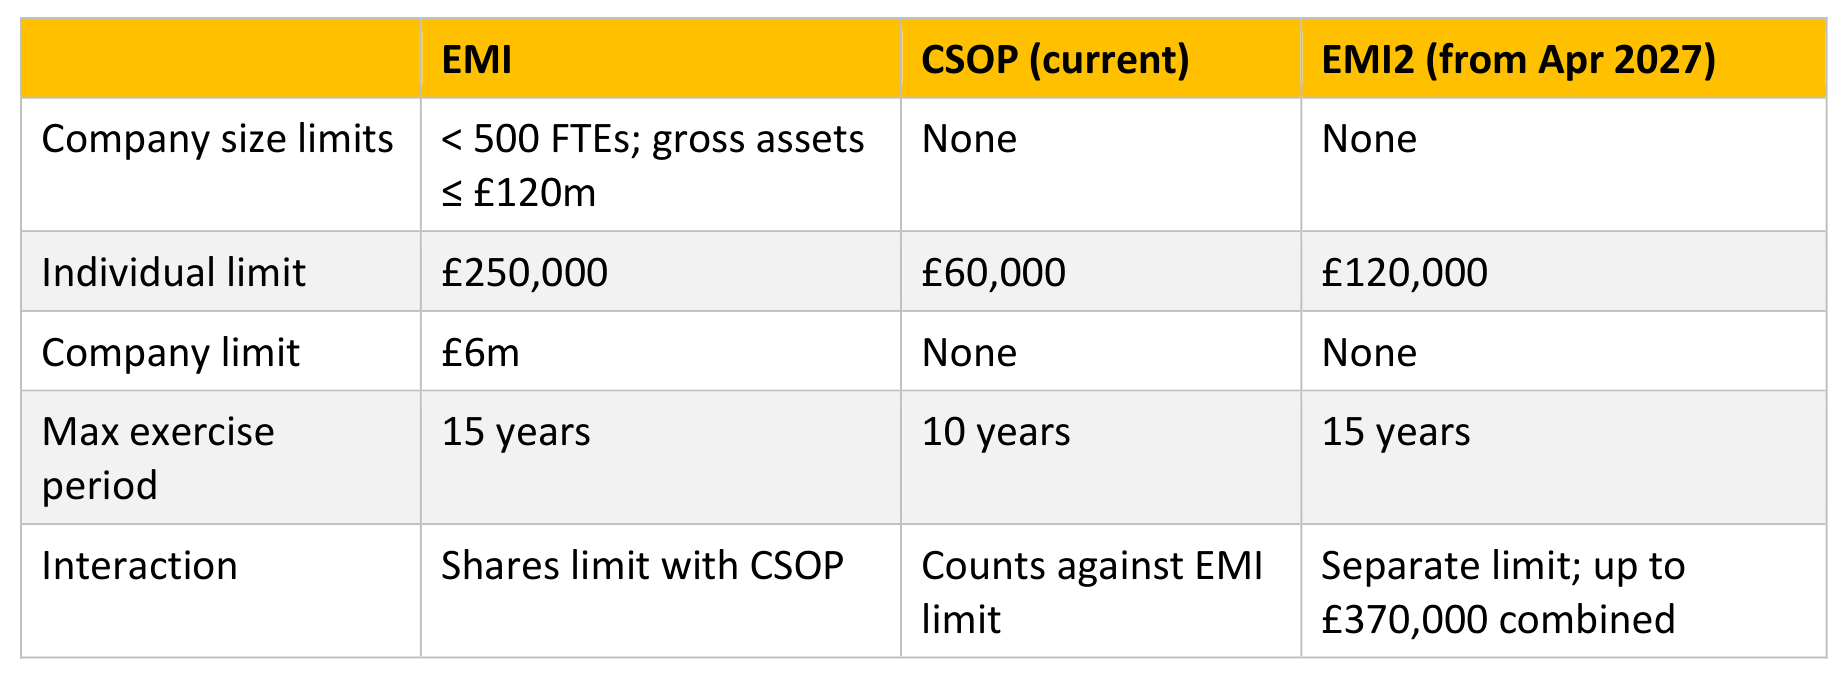
Further EMI changes from 6 April 2027:
These build on the April 2026 EMI expansion (500 FTEs, £120m gross assets, £6m company limit, 15-year exercise window).
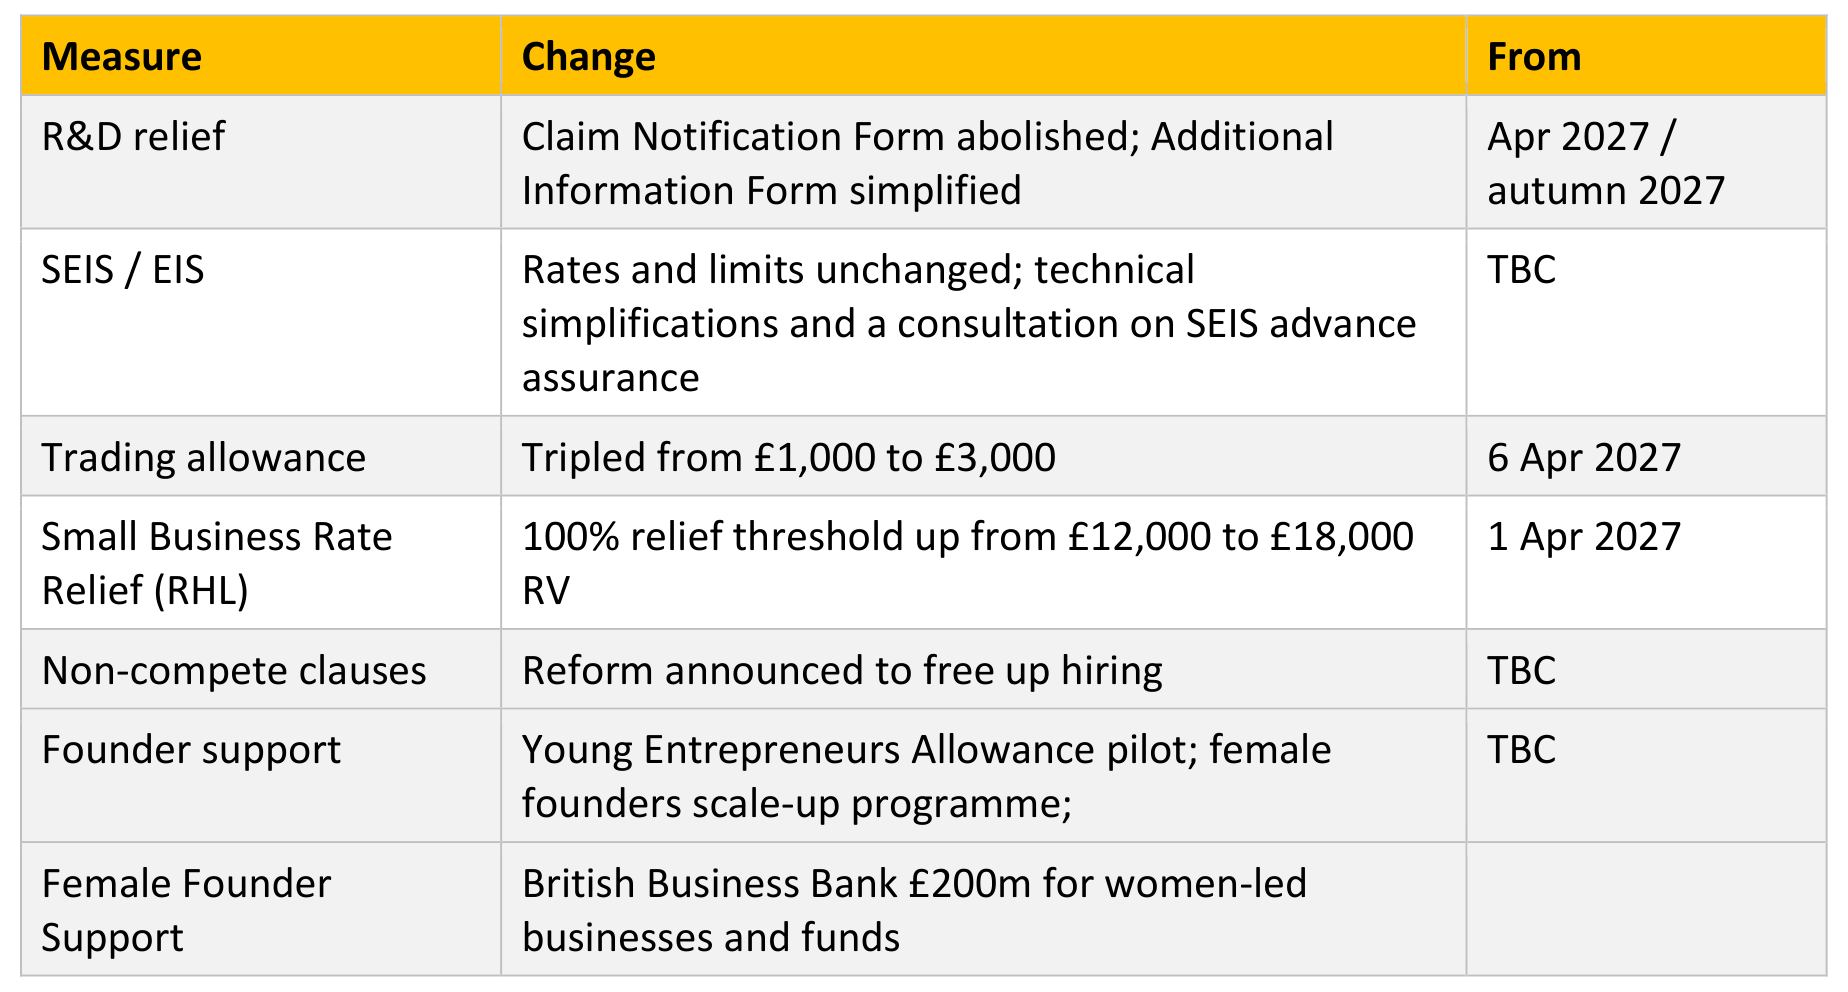
Other key measures
No broad-based tax rises; revenue comes mainly from banks, savers, landlords and slower capital allowances.
Practical implications
Founders and early investors
The new Founders Relief announced with a lifetime allowance at 10% for up to £10m of Capital Gain sounds great and applies to early investors as well. However, the conditions appear to be very restrictive and based on encouraging super-fast scaling companies with an annual revenue of £10m or more.
To put this into context based on ONS analysis there are over 2.7m companies registered in the UK who are registered for VAT (i.e. a turnover of over £90k) of which between 800,000 to 900,000 have a turnover or revenue of more that £500k. ONS estimates that only 38,000 companies in the UK have a revenue of over £10m. Whilst the headline sounds really great unless the conditions are varied significantly there is very little prospect of this being a realistic or attractive incentive for Founders and Entrepreneurs.
The only way to influence this is to respond to the technical consultation Founders’ Relief: technical consultation – GOV.UK – please do take the time to respond.
At the same time the reduction to BADR from £1m to £500k (only a £30k tax differential will have a much greater impact on Founders, EMI holders and investors).
On a more positive note the changes to EMIs and EMI2 are very welcome as well as a number of other changes implemented in the Budget.
There are lots of things to consider here so please do get in touch if you’d like to discuss.
This article is for reference purposes only. It does not constitute legal advice and should not be relied upon as such. Specific legal advice about your specific circumstances should always be sought separately before taking or deciding not to take any action.
A commercial lease renewal can look straightforward. However, simply changing the dates and rent can preserve historic liabilities, outdated provisions and arrangements that no longer reflect the property or the parties’ commercial needs.
Joelson LLP has joined the Legal Sustainability Alliance (LSA), the UK's leading sustainability network run by law firms, for law firms.
Joelson advises Codex Capital on investment in international branded payments and rewards group Norell